
Jackson Hole 2026. No Dots. No Guidance. No Change. Yeehaw!
Global Macro | Technology | Corporate Development | Investment Strategy
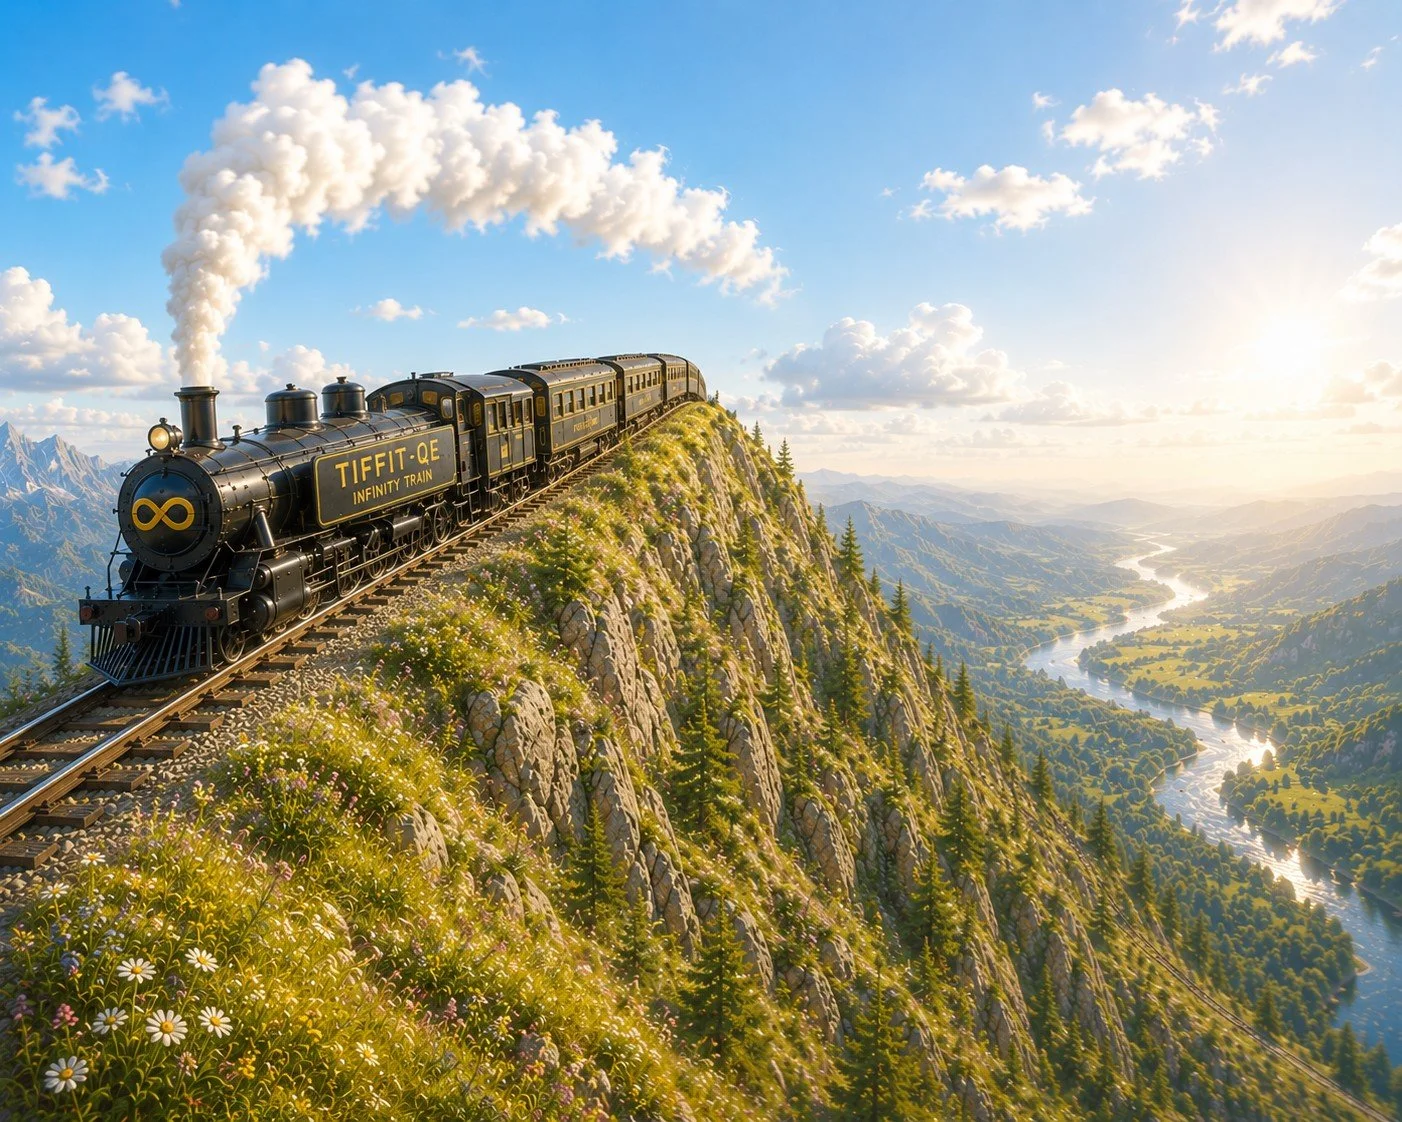
“TIFFIT-QE Infinity Train to nowhere, somewhere off the coast of Japan”. Copyright 2026. nextlevelcorporate. nextlevelcorporate prompts, AI image.
TL; DR
Every year, Jackson Hole gives us something to talk about.
This year, I’m not going to try. Instead, here’s the setup going into Jackson Hole 2026.
This is Kevin “No Dot” Warsh’s first Jackson Hole as Fed Chair.
He has refused to submit a dot for the dot plot, refused to provide meaningful forward guidance and told markets to play the ball, not the referee.
He also has five task forces reporting back by December.
So, what exactly do we expect him to say tonight?
Not much.
No Dot isn't going to raise rates and upset Trump. He isn't going to cut rates and upset the bond vigilantes. Until his five task forces report back in December, the most likely outcome is that he stays exactly where he is.
The more interesting story is Treasury Chief, Scott Bessent
While No Dot refuses to give guidance, Bessent is increasingly using Treasury's balance sheet to influence the part of the curve that matters most to the Treasury.
The move is simple. Sell short-dated Treasuries and buy longer-dated Treasuries.
It isn't QE. No new reserves are being created. It isn't traditional Fed yield-curve control. It is, essentially, Treasury reallocating its existing ammunition across the curve. No new money is being created. It’s not liquidity. It’s just recalibration to bend the curve back into a palatable shape.
And the small quantum matters less than the signal.
When 20 and 30 year yields pushed above 5.3%, they moved into territory Treasury clearly wasn't comfortable with. Those yields feed directly into long-term borrowing costs, including mortgages, and eventually into the wider economy.
Bessent stepped in.
The question now is whether the market interprets that intervention as a soft ceiling on long-term Treasury yields.
And this is where TIFFIT comes back into the picture. The QE Infinity train to nowhere doesn't care which institution is driving the locomotive. It can be the Fed. It can be Treasury. It can be Treasury coordinating with the Fed, Japan or other major Treasury holders.
The mechanism can change. The driver can change (now Bessent). The destination doesn't.
The train accelerates and decelerates but doesn’t stop. And it only derails if enough sovereigns and Treasury holders lose faith in the U.S. dollar and U.S. Treasuries. That would threaten the world's most important collateral base, the Treasuries underpinning the Eurodollar system, global trade and vast amounts of dollar-denominated debt.
That is why intervention is not optional.
So, my Jackson Hole call?
No Dot says very little, with his silence being the signal. Nothing to see here, watch Bessent and the market, not me. Bessent watches the long end, and plays a game of chicken with Japan, China, Belgium and vigilantes. Chicken turns into whack-a-mole if Japan dares to let BoJ yields rise too far.
And the market watches both while the smell of future liquidity fills the air. Why else are Bitcoin and gold reacting?
The really interesting story begins after Jackson Hole, as U.S. officials continue talking to Japan and other major holders of U.S. Treasuries.
Jackson Hole may produce very little news.
But that silence and the setup around it tells us plenty.
See you in the market 🖐
Mike
Macro first. Strategy second. Deal third.
An independent corporate development studio, established in Perth in 2001, advising you when — and when not — to do the deal. In 25 years, that discipline has been the difference.
This content is copyright NextLevelCorporate. It is not advice and it is provided for informational purposes only. NextLevelCorporate and logo are registered trademarks. All rights reserved.