
Metals Roundup Jul'26: More shrinkwrap
“Honey, we shrunk the metals bull” Copyright 2026. nextlevelcorporate. nextlevelcorporate prompts, AI generated image.
Summary for July 2026. Slowing prices.
There’s a capex boom going on, although most of it is in the Americas which doesn’t buy its rocks from us.
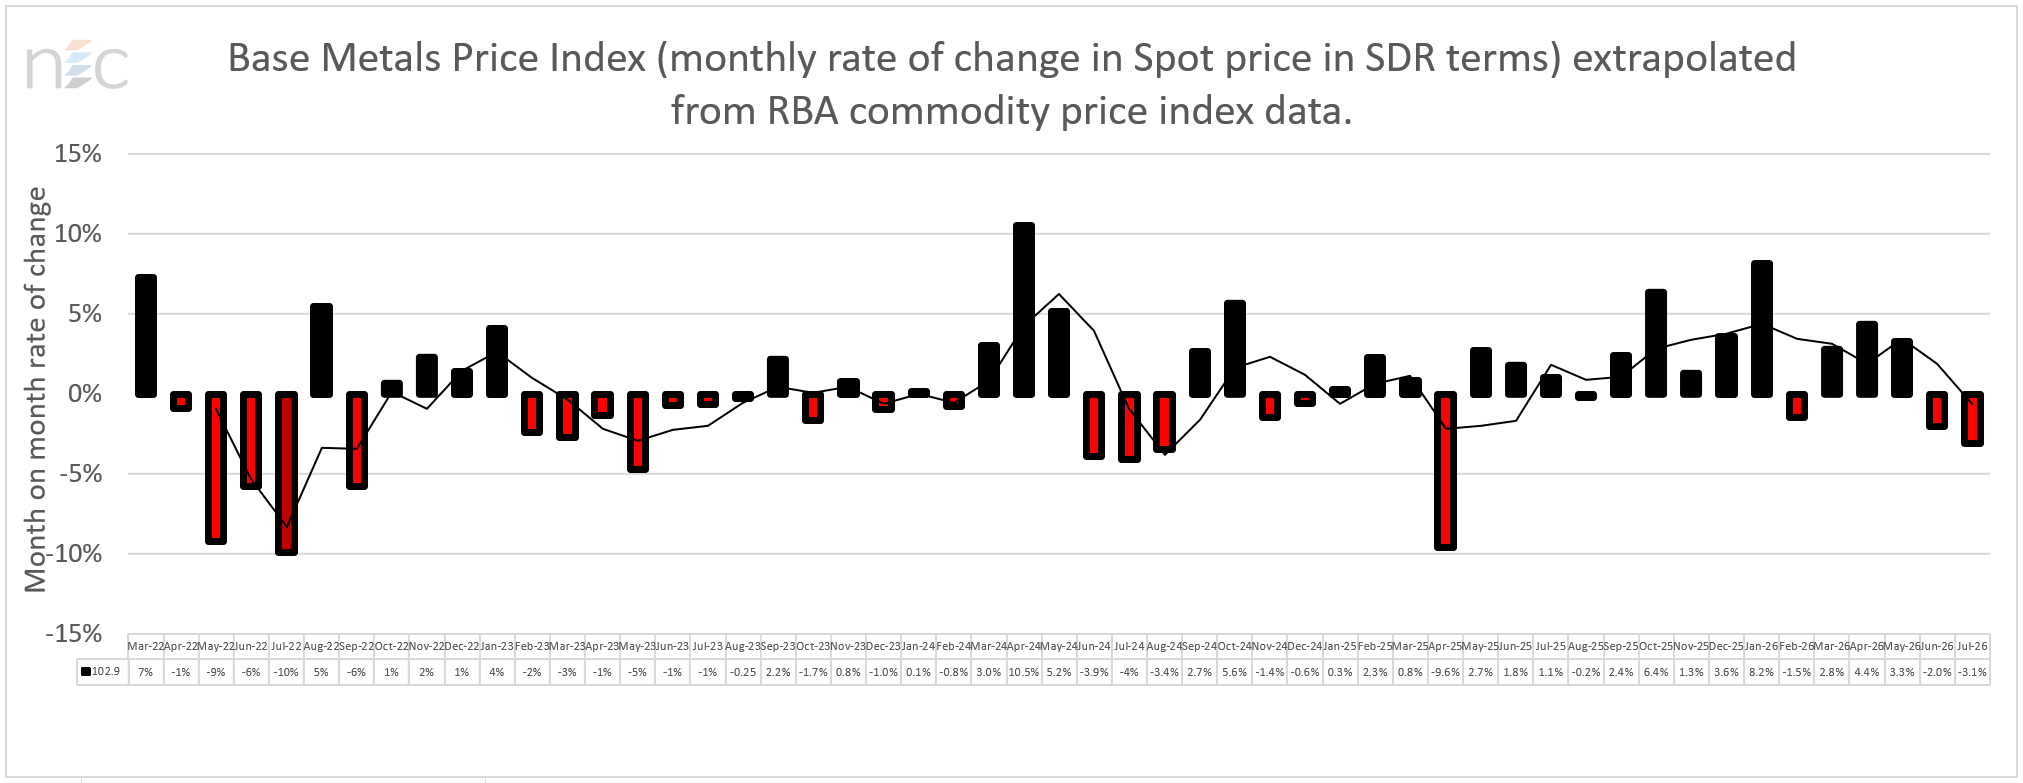
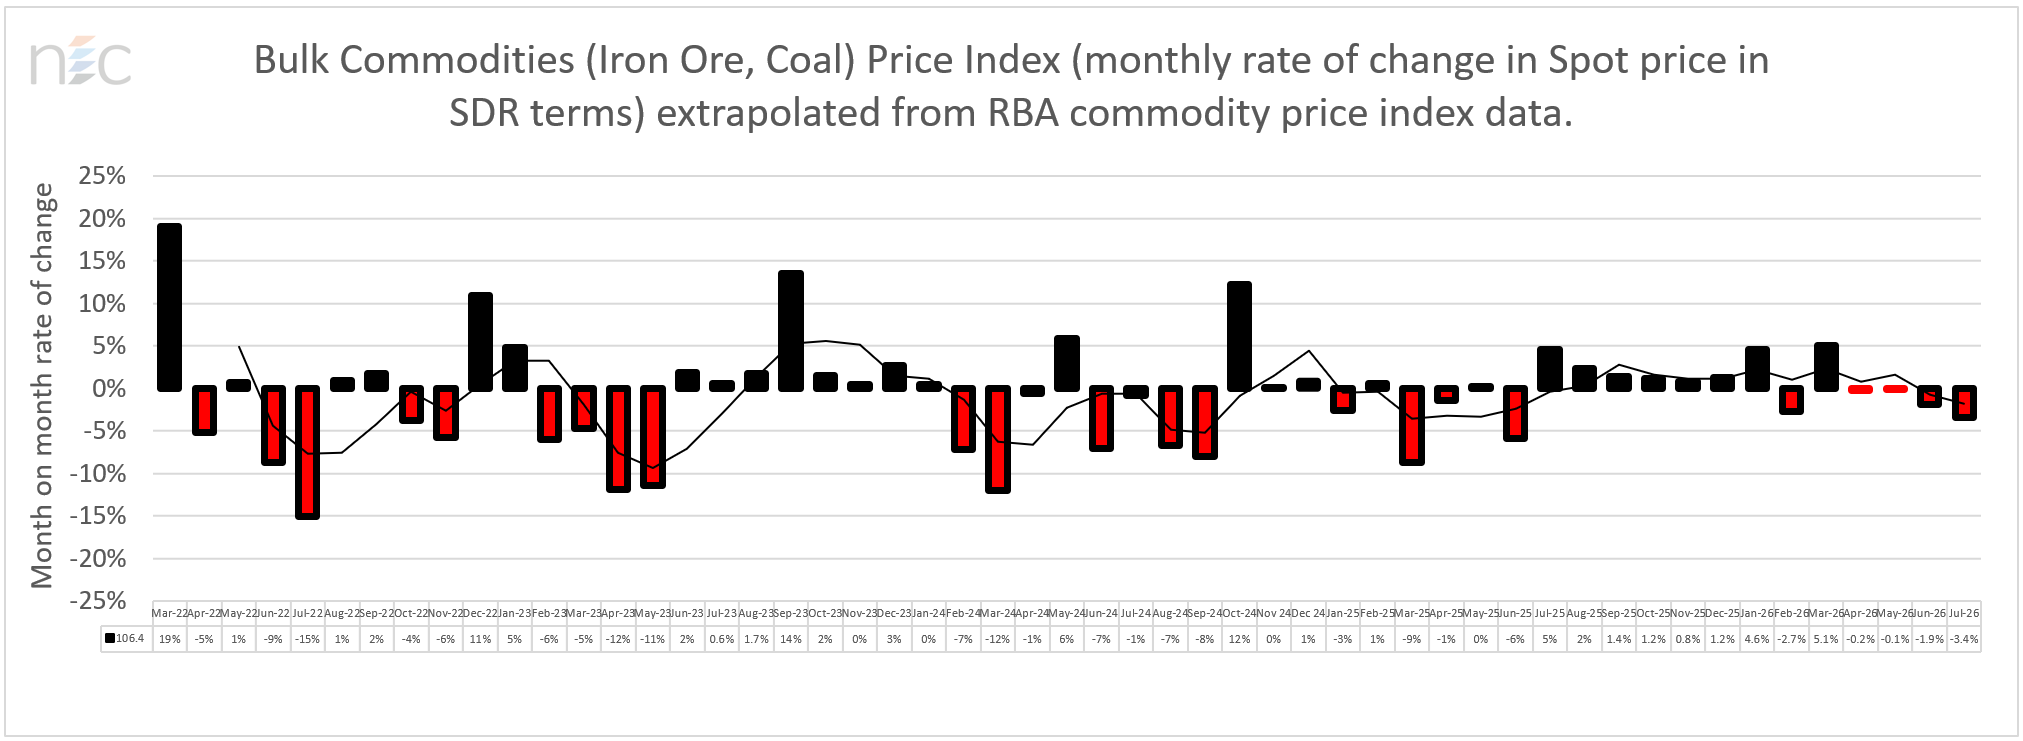
Metals Roundup tracks Australian export prices for bulk minerals and base metals, specifically the month-on-month rate of change. In July, both base and bulk prices slowed faster than in June.
This is not a function of the MAG7 infrastructure level buildout. It’s a function of lukewarm China demand. China has only just started to add more stimulus into its economy. It will take time to work through. If it does. That and a strong USD have their collective feet on the neck of the next commodities cycle.
Base metals
Copyright, NextLevelCorporate Advisory
Bulk minerals
Copyright, NextLevelCorporate Advisory
Base metals are now in their second month of slowing prices. Bulk commodities have been flat-to-negative for four straight months: April –0.2%, May –0.1%, June –1.9%, July - 3.4%. A faster pace of slow.
Bulks are the China-construction proxy, and construction is still soft. Iron ore and coal are much more directly tied to Chinese steel output and property activity than base metals are. Beijing's "anti-involution" push to rationalise steel capacity, plus a property sector that still isn't showing a durable recovery, is a more parsimonious explanation for four flat-to-down months than anything happening to the dollar.
Base metals had their own supply-side story driving the January-April run, separate from currency, mine disruptions and tight refined-copper availability pushed base metals up 8.2% in January alone. Some of June's giveback looks like ordinary mean-reversion and profit-taking after a four-month run, on top of the USD move. But then July doubled down on the slowdown.
Both price complexes are in a downtrend.
Other industrial commodities of interest
⚗🧲☢ Energy minerals (ex-coal and oil)
The July 6, 2023, price high for LME Lithium Hydroxide CIF was US$46,046.
On the last LME trading day of July, it printed US$19,130/t, still more than 58% down from its July 2023 peak. Petroleum supply shocks and shortages leading to some substitution/switching to EVs had been driving the increase but since the Trump TACO on Iran the pain seems to be a memory. But we haven’t seen the last of troubles in Hormuz.
On the other hand, sodium and other battery chemistries are being spoken about more often, with higher levels of confidence for certain applications.
Uranium was trading lower at the end of July, but still solid support at US$86/lb. I expect uranium prices to continue “up to the right” although not in a straight line. And I continue to note uranium is not controlled by China and is a purer form of exposure to zero-emissions electricity.
Fossil fuels are now more than ever making a structural comeback as I’ve been suggesting.
🪔 Oil
On February 28, 2026, the United States and Israel launched coordinated airstrikes on Iran under Operation Epic Fury, targeting military facilities, nuclear sites, and leadership. The response was swift and economically devastating. Shipping traffic through the Strait of Hormuz virtually ground to a halt with a handful of vessel movements. That narrow passage through which around a fifth of global oil production flows, and which also transits around 45% of global sulphur exports needed in the production of fertiliser. Add to that Iran's missile attack on Qatar's Ras Laffan (the world's largest LNG liquefaction plant) causing extensive damage to Qatar Energy's infrastructure, and halting ~330m m3 of LNG/day (20% of global trade) via the Strait. You can read more here.
And on the weekend, bombing resumed.
Global forces, local impact
This is what the current macro spells out for your corporate development and investment strategies, if you're in Australia.
Corporate development strategy. We continue to see higher rates for longer affecting certain mineral projects as a result of discounting future cash flows at higher WACCs, inflated capex, and borderline debt serviceability. In its place, more M&A. This is accelerating. Capital is selective, but for favoured sectors, gold, rare earths and uranium, it's strong, even with lithium down again. This can change quickly, especially for metals that behave cyclically even though the long-term thesis is still intact. And the impact on exploration companies as a result of a return to CGT indexation in Australia is starting to have an effect on Aussie explorers.
Investment strategy. Like last month, equities capitulation and peak yields are still not in, we're not done yet, there’s more room to run on yields and stocks, so we wait. Crypto capitulation has probably already happened and it’s starting to bounce. Are NFTs really back? Liquidity is steady but not stimulative, so a bubble-then-crash is unlikely. And Scott Bessent may have signalled where his pain level is with long bond yields, although the market still isn’t buying that, nor No Dot Warsh’s big hat no cattle speech at Jackson Hole on Friday. Yields are still rising. So is gold. So is crypto.
In the meantime? Hard commodities super cycle on pause, interest rate cuts/hikes on pause but tilting slightly more hawkish, with plenty of project and investment volatility until further notice as most major economies navigate narrow swim lanes between fighting sticky inflation and protecting the long end of the curve.
See you in the market 🖐
Mike
Macro first. Strategy second. Deal third.
An independent corporate development studio, established in Perth in 2001, advising you when — and when not — to do the deal. In 25 years, that discipline has been the difference.
This content is copyright NextLevelCorporate. It is not advice and it is provided for informational purposes only. NextLevelCorporate and logo are registered trademarks. All rights reserved.