
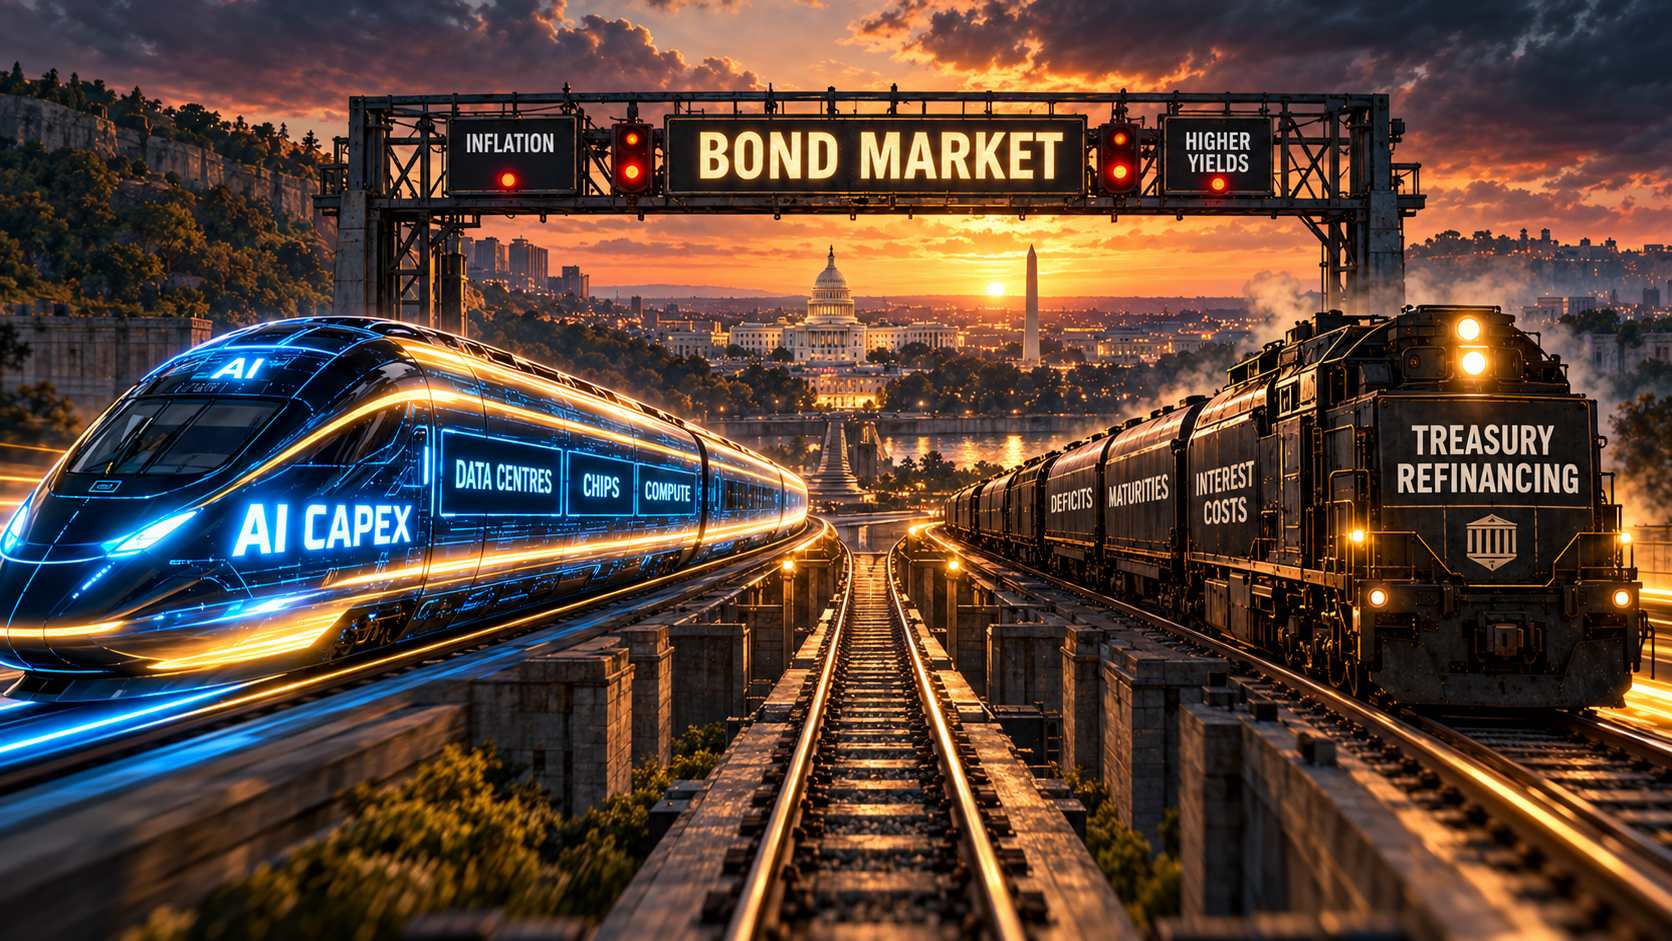
“Two train sidings, one infinitely looping track”. Copyright 2026. nextlevelcorporate. nextlevelcorporate prompts, AI generated image.
TL; DR
The risk is quieter and broader than many people think. A bond market increasingly asked to fund two of the largest, most duration-hungry borrowers on the planet at the same time, with no spare capacity to comfortably absorb both at today’s prices.
Everyone keeps reaching for the dotcom comparison to argue AI is either a bubble or it isn’t. On the fundamentals, it isn’t. Combined annualised revenue at Anthropic and OpenAI alone is now running above US$115 billion, Anthropic, at roughly $65 billion and OpenAI near $50 billion as of the end of September, nothing like Looksmart’s $15 million revenue back in the day.
Memory chipmakers are posting gross and operating margins in the 75-85% range industry-wide, SK Hynix reported a 76% operating margin last quarter and Nanya a record 85.7% gross margin (a 6.2 percentage points improvement from that in the previous quarter), against the 30-45% margins the memory business ran on for decades and well above where Lucent was sitting before it went under back in the day. Today Micron is punching out 85% margins and No Dot Huang doesn’t have any more chips to sell you.
Moreover, a meaningful share of today’s AI infrastructure build is being locked in through customer prepayments and take-or-pay contracts rather than speculative debt, a structural difference from telcos funding the fibre build with junk bonds and hoping demand would eventually show up.
And where roughly 97% of the fibre laid in the dotcom years sat dark for years afterwards, neocloud and GPU providers are now reporting utilisation on contracted capacity in the 80% t0 90% range. Compute itself isn’t getting cheaper either, GPU rental prices are up roughly 18% over the past year on GetDeploying’s index, with premium chips like Blackwell up far more, a genuine shortage, not a 2000-style price collapse.
On every one of those measures, AI in 2026 looks nothing like dotcom in 2000.
But that comparison answers the wrong question. It tells you people are using what’s being built and paying for it. It says nothing about whether everyone who wants to build more of it can get funded to do so, at a price that still works, in a bond market where the U.S. Treasury is also trying to borrow at scale.
My read is that if a bigger downdraft comes, it won’t look anything like dot com. It’ll look like a financing problem with hyperscaler capex competing directly with No Brake Bessent’s own refinancing for the same pool of long-duration capital, at the exact moment inflation isn’t under control enough for bond sellers to stop selling, nor for No Dot Warsh to cut rates and make the problem disappear.
Where we left it
In No Dot Warsh, task force number four was explicitly about the AI productivity bet, the idea that if AI can grow nominal GDP faster than debt accrues, the administration inflates away the debt organically without the political cost of overt monetisation. In Bessent Is The Fed Now, Treasury doubled its long-end buyback operations the day after the 30-year hit its highest level since 2007, a direct intervention to manage yields rather than wait on the Fed. In Are we becoming France, the numbers were already large, hyperscaler capex at roughly US$800 billion in 2026 heading toward US$1.2 trillion in 2027, and a semiconductor index that had already corrected 24% from its June highs.
This piece connects those threads. The AI productivity bet and the TIFFIT QE Infinity train to nowhere are not running on separate tracks. They might spend some time on the sidings, but they’re increasingly running on the same track. And as we explained in The Treasury Market Is the Load-Bearing Wall, that track is global, circular, infinite, and maintains the load-bearing walls of the global financial system.
The borrowing is real, and it’s enormous
This isn’t abstract.
Meta has financed a data centre build through an off-balance-sheet bond deal running into the tens of billions.
Amazon has pushed dollar issuance out to 2076.
Alphabet has layered long-dated dollar debt with sterling paper running to 2126.
Oracle has leaned hard on debt to fund its own capacity commitments.
These aren’t speculative issuers either, they’re some of the most creditworthy companies on the planet, which is exactly why the bond market keeps absorbing the supply without blinking on quality.
Reverse crowding out, and why that term matters
Economists have spent decades worrying about government borrowing crowding out the private sector. What’s showing up in 2026 is closer to the opposite.
Ed Yardeni calls it reverse crowding out, AI hyperscalers issuing debt that’s almost yield-agnostic, because they believe the returns on the build-out justify paying whatever the market asks.
🚩 Capital that would otherwise go into Treasuries goes into corporate AI paper instead, and Treasury yields have to rise to clear the market, not because corporate spreads are blowing out, but because Treasuries are losing the bid.
No Brake Bessent has confirmed as much himself, describing the corporate issuance as yield-agnostic and noting the market has adjusted “not through higher corporate borrowing costs relative to Treasuries but through higher Treasury yields themselves.”
That’s about as direct a confirmation as you’ll get from a sitting Treasury secretary that his own refinancing is losing a bidding war to the biggest names in tech.
The numbers back it up. JPMorgan puts 2026 hyperscaler debt issuance at roughly $320 billion, equivalent to 68% to 70% of new long-term Treasury borrowing over the same period. Nomura estimates big tech’s borrowing alone equals around 25% of Treasury’s net issuance of notes and bonds to private investors, five times its share in 2025. Bank of America attributes roughly 0.3 percentage points of this year’s rise in the 10-year to AI-linked corporate debt and mortgage-backed securities combined.
That’s also why No Dot Warsh feels the Treasuries market is tightening, without FOMC needing to intervene, and why we probably won’t see any real move from him until his task forces report in December, and/or he starts to talk about the balance sheet.
Why this lands hardest exactly where Bessent’s already fighting
Data centre assets have long economic lives, so hyperscalers are terming out their debt to match. Across 2025 and 2026, hyperscalers have placed 41% of their issuance beyond 15 years against 16% for the broader investment-grade index, and their weighting in the 26-year-plus bucket is two and a half times the market’s. Microsoft, notably, hasn’t termed out its 2026-27 capex yet, which means there’s more long-dated supply still coming.
That’s the same stretch of the curve Bessent moved to defend in August. The 30-year buyback wasn’t only a response to a soft auction or raw deficit-driven supply. It was Treasury stepping directly into a market where it’s now competing, duration bucket for duration bucket, with the largest companies in the world for long-term demand. This is the mechanism behind the long-end pivot I wrote about last time, just with a second borrower now named explicitly in the reporting.
But I think it’s worse, because the semis inside DCs might be obsolete well before the cement and steel holding up the fort is. And that won’t play out well for ROI, for viability, or for compute pricing, especially if there is a credit crunch.
Is this actually dangerous, or just loud?
For the sake of being fair to the other side, if there are sides, JPMorgan’s own strategists estimate the hyperscaler group could absorb another $1.5 trillion in debt without pushing leverage ratios above the broader market average. They also suggest credit spreads on hyperscaler bonds have only widened modestly, 10 to 22 basis points across tenors.
The stress isn’t showing up yet as a credit event, hyperscalers aren’t being priced like weak borrowers like the over-levered neoclouds, which will have their day, but just not today.
It’s showing up as a rates event, the diffuse, economy-wide kind that raises the discount rate on everything, not the sharp, idiosyncratic kind that takes down overleveraged borrowers first.
That’s exactly why the dotcom comparison misleads people into looking for the wrong kind of break.
Nobody’s betting on a Lucent-style bankruptcy here. The risk is quieter and broader, a bond market increasingly asked to fund two of the largest, most duration-hungry borrowers on the planet at once, with no spare capacity to comfortably absorb both at today’s prices.
The race within the race
This is where it connects back to task force four. The administration’s bet, as I read it from No Dot’s own framing, is that AI-driven productivity can grow the economy faster than the debt burden accumulates.
But if the AI build-out itself is now a structural driver of higher long-term rates through reverse crowding out, the thing that’s supposed to outrun the debt is simultaneously making the debt more expensive to carry.
That’s not a contradiction that resolves itself quickly. The swim lanes are narrowing. And the usual release valve, a Fed turning on the liquidity taps and letting cheaper money absorb the strain, isn’t fully available. No Dot Warsh spent Jackson Hole warning that underlying inflation trends haven’t meaningfully improved and left hikes on the table, and at last week’s FOMC he confirmed the committee wants to see more data before moving either way.
So, here’s the deal. You’ve got AI capex demanding long-duration capital, Treasury demanding long-duration capital to refinance $40 plus trillion in past government deficits and spending, and a Fed chair who can’t simply flood the system to make both cheaper without reigniting the inflation problem he’s already on record worrying about, and because ultimately, it’s No Brake’s call. He’s driving the train.
Three borrowers, one bond market, one inflation constraint on the QE Infinity train to nowhere which is the easiest, and eventual fix. That’s the actual setup.
🚩 This is a financing story, not a valuation story. It’s not dot com.
What this means for corpdev and investing
First, keep discount rates conservative, but for a more specific reason than general caution. If hyperscaler issuance keeps running at 2026’s pace and Microsoft still has to term out its own capex, long-end rates have a structural bid against them from both government and corporate supply at once. WACC assumptions should reflect a higher-for-longer financing environment driven by two borrowers, not one. And weakness in precious metals coupled with higher rates will have stern implications for those preparing a BFS for their project. No directional change on the weakening availability and cost of financing, just reiteration.
Second, the anti-debasement trade still holds, arguably more so but it will take time. If this tension resolves the way TIFFIT predicts, not through austerity, but through policymakers eventually finding a way to make money cheaper for everyone after the U.S. mid-terms, gold and crypto remain the natural hedge against whatever mechanism gets used to paper over a bond market currently being asked to fund more than it comfortably can. But there will be downdrafts in the meantime, like last week. And with further downdrafts in equities to come, most likely lit by the mid-terms and Anthropic, precious metals will most likely come under further pressure well below 4,000. This probably means our miners will come under further pressure.
Third, for Australian corpdev specifically, this is now a global capital competition and risk-off sentiment story, not just a domestic rates story. Any business raising long-duration debt internationally is doing so into a market where the largest names in tech and the U.S. Treasury are simultaneously bidding for the same long-term capital. Price your financing accordingly. Oh, and Japanese debt is not as cheap as it used to be so if you’re counting on that, best you check current positioning. In addition, raising domestically, either debt or equity is a little harder as government policy remains inflationary, rates stay higher for longer, new taxes penalise risk and aspiration, lower property prices dampen the wealth effect, and the bank of mum and dad gets pinched. This increases the domestic cost of capital and weakens sentiment and the propensity to spend.
Net, watch Treasuries and corporate debt duke it out, that’s how you’ll know when and where the TIFFIT QE Infinity train to nowhere shows up next, with No Brake Bessent at the throttle and No Dot Warsh in the fireman’s seat, shovelling just enough coal to keep the pressure up without that dynamic duo ever naming the destination or when they’ll pay for the fuel that’s on account. And the second eye needs to be focused on the mid-terms and whether there is a blue wave because that might signal a political headwind to the AI trade.
Abracadabra. See you in carriage 5 (which, by the way, is the debasement sleeper carriage) 🖐
Mike.
Macro first. Strategy second. Deal third.
An independent corporate development studio, established in Perth in 2001, advising you when — and when not — to do the deal. In 25 years, that discipline has been the difference.
This content is copyright NextLevelCorporate. It is not advice and it is provided for informational purposes only. NextLevelCorporate and logo are registered trademarks. All rights reserved.