
If AI can outrun the Infinity Train, can it also outrun the bond market?
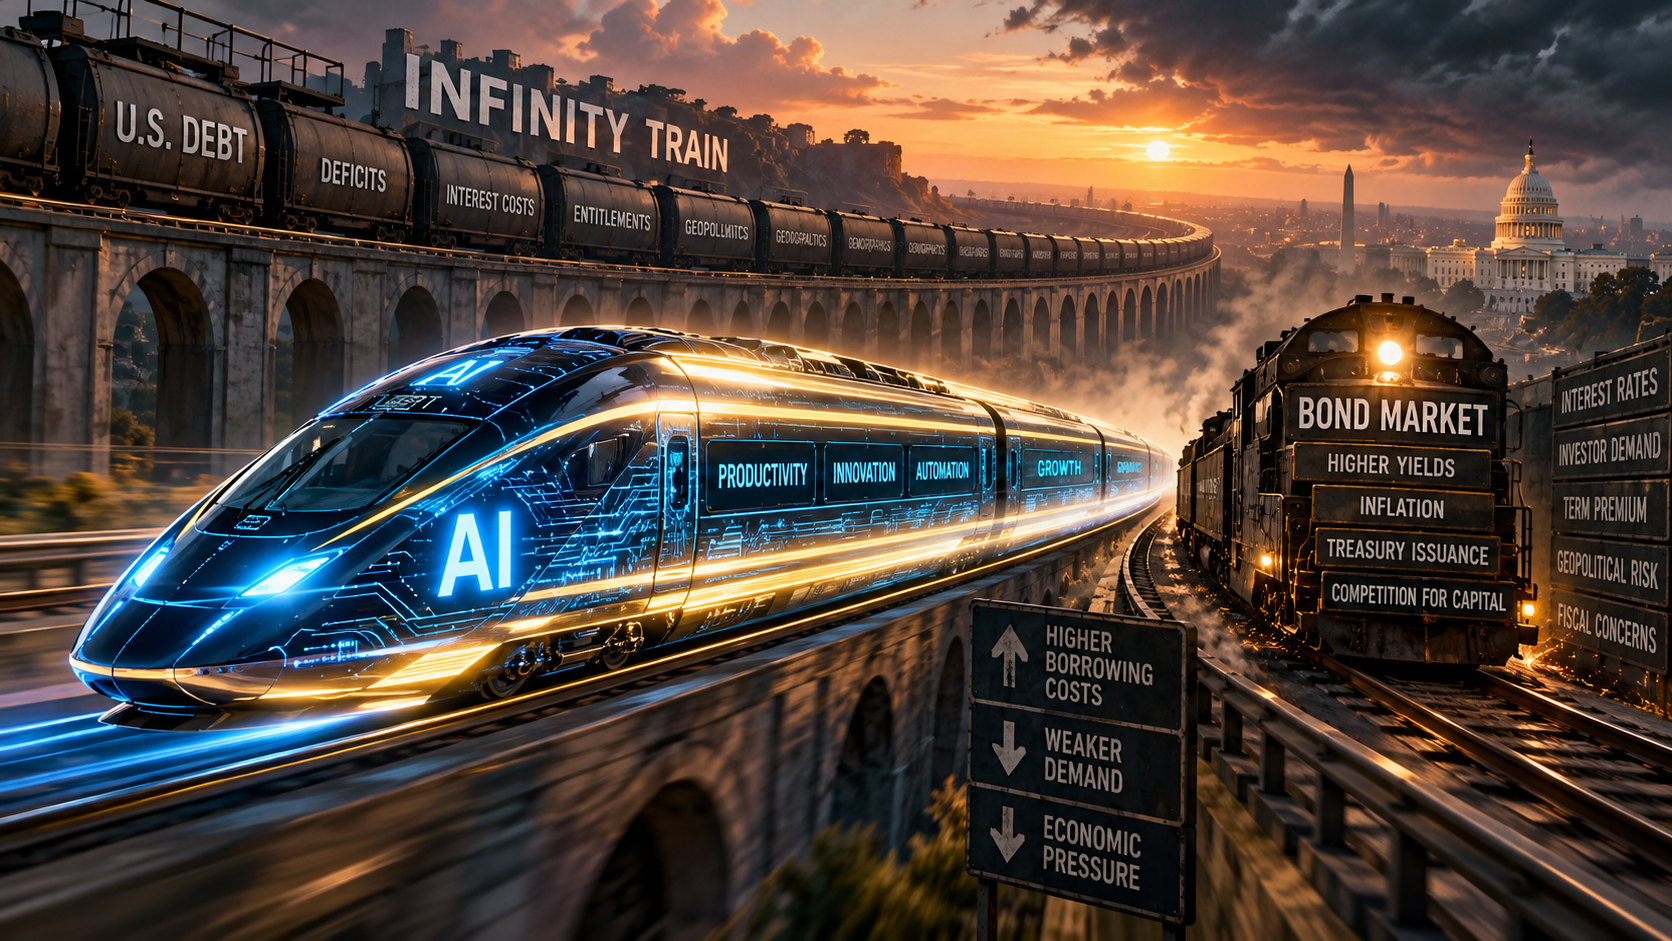
“AI versus bond market” Copyright 2026. nextlevelcorporate. nextlevelcorporate prompts, AI generated image.
America is betting that the Machines can generate enough productivity to outrun the debt. But the financing required to build them could push bond yields higher, squeeze the economy and undermine the very demand needed to make the investment pay. Well, that's an interesting little problem, isn't it?
TL; DR
In my recent article A new Marshall Plan, but can the Machines outrun the Infinity Train? I explored the extraordinarily courageous wager being laid by Trump, Bessent and No Dot Warsh. The idea is that AI, agentic software, robotics and automation can lift U.S. productivity enough to help the economy outrun its enormous debt burden. Run productivity faster than the debt servicing burden.
But there is a second race taking place, and it could prove just as important.
The Machines need capital to be built. The U.S. Treasury needs capital to refinance existing debt and fund continuing deficits. Corporate America needs capital to invest, expand and employ. And all of them are increasingly competing for the same pool of savings.
If that competition pushes bond yields higher, the cost of building the Machines rises. Higher borrowing costs can then squeeze businesses and consumers, weakening the demand for AI services just as the hyperscalers need it to accelerate.
Yikes.
The question is no longer simply whether AI can outrun the Infinity Train. It is whether the Machines can generate their productivity dividend before the bond market makes the race considerably more expensive.
Let's dig in.
First, follow the money
The scale of the investment is extraordinary. Goldman Sachs has forecast that the five largest U.S. hyperscalers will spend approximately US$800 billion on capital expenditure in 2026, rising to around US$1.2 trillion in 2027. These figures are estimates of the companies' spending, not a precise measure of AI-only expenditure, but they give us a sense of the scale of the build-out.
And that is just the beginning of the story. Data centres need chips, electricity, cooling, buildings, networking and transmission infrastructure. The Machines need an awful lot of physical stuff before they can start doing an awful lot of useful work.
So, who pays the bill?
Well, ultimately, businesses, consumers and governments will buy AI services because if they generate sufficient economic value. Companies might automate customer service, accelerate software development, improve manufacturing or create products that were previously impossible. Consumers might pay for subscriptions, while advertisers and technology companies fund other applications.
But here's the catch. Some AI companies raise capital from investors and then spend that capital buying computing capacity from hyperscalers. That creates genuine revenue for the cloud provider, but it does not necessarily prove that the ultimate customer is generating enough economic value to sustain the expenditure.
Money can make quite a journey around the financial system without creating an equivalent amount of new wealth. Well, we've seen that movie before and spoke a little about it last week in The financial lasagne of a hyper-financialised world.
The important distinction is between investment in the Machines and productivity generated by the Machines. The first is already happening. The second has to earn its keep.
How much revenue is enough?
Let's run a quick sniff test. We don't need a 20-tab spreadsheet, or a PhD to establish the broad economics.
Assume a six-year useful life for the infrastructure, a 10% required annual return and a 30% free cash flow margin. Using a standard capital-recovery calculation, each US$1 trillion invested requires approximately US$230 billion in annual cash flow to recover the capital and earn that return. At a 30% margin, that implies around US$767 billion in annual revenue per US$1 trillion invested.
Hyperscaler capex is forecast to rise from US$800bn in 2026 to US$1.2tn in 2027. Using the above metrics this implies (illustrative only) annual revenue hurdles of US$613bn and US$920bn respectively, simply to recover each investment cohort.
Importantly, these are steady-state annual revenue hurdles for each year's investment, not revenue required in the year the money is spent. The calculation is illustrative, not a forecast, and it is not directly comparable with Goldman's own break-even estimate of approximately US$300 billion in annual AI revenue or its reported estimate of US$636 billion to achieve a 30% return on invested capital. Those figures use different assumptions and definitions.
The point is not that the investment cannot work. It is that the numbers require substantial, sustainable customer demand and attractive cash margins. The hyperscalers must do more than build capacity. They must sell enough computing power and AI services, at prices that leave enough cash behind, to justify the capital committed.
And that brings us to the next question. What happens if the cost of financing the Machines rises before the revenue arrives?
Enter the bond market
Infinity train driver Bessent’s Treasury has a rather large financing requirement of its own. It must refinance maturing government debt and issue additional debt to fund continuing budget deficits. Meanwhile, the hyperscalers are increasingly using corporate bonds to help finance their AI infrastructure programs.
Both are asking investors for capital. So are companies across the rest of the economy.
This does not mean the hyperscalers are necessarily borrowing recklessly, nor does it mean their borrowing alone explains rising Treasury yields. However, the scale of their investment adds another significant claim on the market for capital at a time when the U.S. government is already issuing enormous quantities of debt.
Fed Chair No Dot Warsh has identified competition for capital from hyperscaler borrowing as a factor contributing to pressure on long-term Treasury yields. That is an important observation because it connects the AI build-out directly to the cost of financing the wider economy.
When investors have more bonds to absorb, yields may need to rise to attract sufficient demand. The relationship is not mechanical, because savings, foreign demand, bank balance sheets, regulation and expectations about future growth all influence the outcome. But the basic economics are straightforward. Capital is not free, and an enormous increase in the demand for it can change its price.
Now consider the U.S. Treasury. It needs investors to keep buying its securities at manageable yields. Higher yields gradually increase the cost of refinancing government debt and make an already difficult fiscal position more expensive to sustain.
The hyperscalers, meanwhile, need financing to keep building. Corporate America needs financing to invest. Households need affordable credit to spend. Everyone wants capital. Everyone would prefer it to be cheap. And nobody has discovered a way to make an unlimited supply of it appear without consequences.
Well, except perhaps the QE Infinity train to nowhere which has developed a rather impressive collection of ways to keep the financial plumbing moving.
The Fed can pull the brakes, but what about the long end?
This is where the distinction between short-term and long-term interest rates becomes critical.
If inflation remains persistent, the Federal Reserve can raise the federal funds rate, pushing up the short end of the yield curve and tightening financial conditions. That makes short-term borrowing more expensive and influences rates across the economy.
But the Fed does not set the ten-year or thirty-year Treasury yield.
Long-term yields reflect expectations for future short-term rates and inflation, together with the term premium investors demand for holding longer-dated bonds. If investors become increasingly concerned about inflation, government borrowing, the supply of Treasuries or the credibility of fiscal and monetary policy, long-term yields can remain elevated even if the Fed eventually cuts its policy rate.
The Iran conflict and energy-price pressures add another complication. Higher energy costs can lift inflation while weakening household purchasing power and increasing the operating costs of data centres and other infrastructure.
So, the Fed faces a difficult trade-off. If it tightens policy to contain inflation, it risks suppressing investment and demand. If it eases too soon, investors may worry that inflation will persist and demand higher yields on long end of the curve bonds.
And if long bond holders lose confidence in the U.S. Treasury's fiscal trajectory or the Fed's ability to maintain price stability, the long end could sell off even as the central bank tries to ease financial conditions.
In other words, the Fed can influence the price of money without having complete control over the price at which the government can borrow for thirty years.
That is important to understand when the government needs to refinance a mountain of debt and the private sector is building a new industrial economy at the same time.
The feedback loop
Now let's put the pieces together.
The U.S. wants AI to generate a productivity boom that helps it grow out of its debt burden. But the infrastructure required to generate that productivity needs enormous investment, which competes with Treasury borrowing and other corporate investment for capital.
If that competition contributes to higher yields, the cost of financing the build-out rises. Higher borrowing costs also put pressure on the Treasury, businesses and households. Investment becomes more expensive, consumption can weaken and companies may become more reluctant to commit to new AI projects.
And here comes the irony.
The hyperscalers are building enormous computing capacity on the assumption that customers will increasingly pay to use it. But those customers operate inside the same economy that is being squeezed by the cost of financing the build-out.
If businesses face higher borrowing costs and weaker demand, they may delay AI adoption or demand a faster, more demonstrable return on their expenditure. If consumers have less disposable income, discretionary spending on AI services may disappoint. If AI companies themselves depend on further investment capital to pay their cloud bills, a tighter funding environment can expose the weakness in the chain.
The result could be excess capacity. The infrastructure exists, the chips are installed, the electricity is being consumed, but profitable demand fails to keep pace with supply.
The Machines may work beautifully. The problem is finding enough customers who can afford to pay for them.
And that is how a technology boom can become a financing problem without the technology itself failing.
Can the Machines outrun the clock?
There is still a compelling optimistic case. If AI, robotics and automation materially increase output per worker, improve corporate margins and create new industries, the U.S. economy could become substantially more productive. Higher output and incomes could support GDP, strengthen tax receipts and make the debt burden more manageable relative to the economy, but growing the economy faster than the debt stack.
But the productivity dividend must actually arrive, and it must arrive at sufficient scale.
Investment does not automatically create productivity. Nor does productivity automatically translate into government revenue or cash available to service private debt. The distribution of the gain matters, as does the speed at which businesses adopt the technology and turn it into measurable economic value.
The timing is everything. The infrastructure must be financed and built before the full benefits are realised. If the gains arrive quickly, the investment could be transformative. If they take longer than expected, financing costs and equipment replacement can accumulate while the revenue needed to support them remains elusive.
There are physical constraints too. Electricity generation, transmission, construction, chips and skilled labour cannot all be scaled instantly. Bottlenecks can raise costs and delay returns. Silicon Valley may be moving at the speed of software, but the electricity grid has yet to acquire the same sense of urgency.
The U.S. is therefore attempting something extraordinary. It is trying to finance a new productive economy while managing an existing debt burden that is already large and expensive to carry. The AI build-out may help solve that problem, but it can also make the problem harder in the short term.
The question is whether the Machines can deliver enough incremental productivity and cash flow before the cost of financing the transition becomes a constraint on both investment and demand.
The investment thesis
For investors, this is a much broader story than whether AI shares are overvalued.
If the machine economy emerges as expected, the opportunity extends across semiconductors, compute, data centres, electricity, transmission, cooling, networking, robotics, industrial automation, advanced manufacturing, critical minerals and the companies that connect the entire productive stack.
But the difference is between owning a technology that changes the world and paying a price that earns an adequate return from that change. AI can be transformative without every infrastructure investment, valuation or financing structure proving attractive.
The businesses worth examining are those with demonstrable customer demand, defensible margins and returns that remain attractive after operating costs, financing and equipment replacement. We should also ask whether AI customers are generating measurable productivity gains or simply adding another expense in the hope that the benefits will eventually appear.
And it’s also worth noting that higher bond yields do not prove the AI thesis is wrong. But they do make the hurdle more demanding. If monetary tightening is required to contain inflation, the resultant pressure on economic activity could affect both the cost of capital and the demand for AI services.
That is the race. The Machines must generate the productivity dividend. The Treasury must keep financing its debt. Corporate America must keep investing. And customers must have enough economic capacity to buy the services that justify the infrastructure 🏁
Can AI outrun the Infinity Train? Perhaps. But can it also outrun the bond market, before the cost of financing the Machines undermines the economy that needs to buy their output?
And that is the $1.2 trillion question we need answered in 2027 before hyperscaler free cash flow runs out.
Well, Infinity train driver Bessent has a lot of work to do and a train load of bonds to sell affordably, but the bond market is not renowned for accepting presidential narrative as collateral.
Abracadabra.
See you in carriage 5 🖐
Mike.
Macro first. Strategy second. Deal third.
An independent corporate development studio, established in Perth in 2001, advising you when — and when not — to do the deal. In 25 years, that discipline has been the difference.
This content is copyright NextLevelCorporate. It is not advice and it is provided for informational purposes only. NextLevelCorporate and logo are registered trademarks. All rights reserved.